
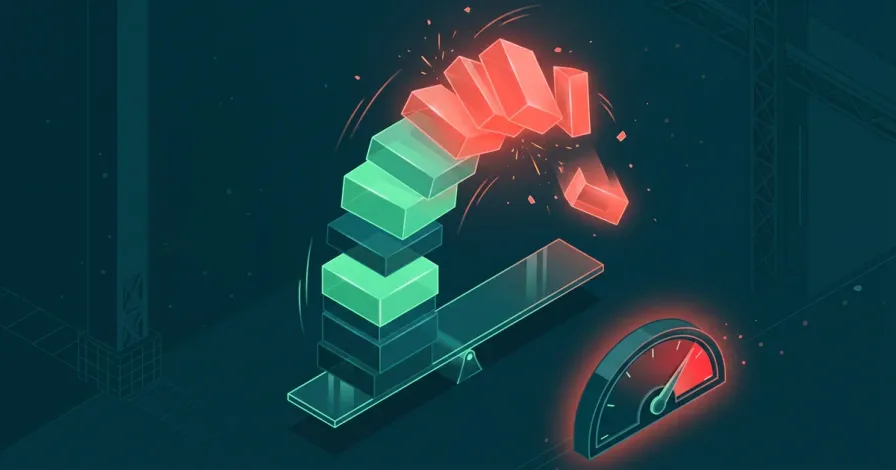
Crypto liquidation is back in the headlines. On Friday 13 November, bitcoin fell below 70,000 dollars for the first time since August and touched 67,770. In 24 hours, CoinGlass recorded 1.64 billion dollars in leveraged positions closed by force, according to CoinDesk. Almost nine out of every ten dollars liquidated were bets on a rise. And over the weekend of 14 and 15 November another wave arrived: between Friday and Sunday, liquidations added up to billions of dollars according to CoinGlass data.
The short answer: a liquidation is the forced closure of a leveraged position when the losses eat up the money you put down as collateral. That money is lost, and in your Spanish income tax return (IRPF) the result does not vanish. If what the DGT (Spain’s Directorate General for Taxation) says about CFDs is applied by analogy, it would be a capital loss in the savings tax base. At CryptoImpuestos we have gone through the mechanics, the European rules and the Spanish tax authority’s criteria to explain what a liquidation is, how it is calculated and how it is declared. Trading with leverage is high risk: here we only explain how it works.
 What happened with the November liquidations?
What happened between 13 and 15 November was not a hack or an exchange shutting down. It was the mechanics of derivatives working as designed. Many traders held leveraged long positions and, when the price fell, the platforms closed them one after another. Of Friday’s total, 916 million dollars were positions on bitcoin.
If you have seen different figures in each outlet, it is not that someone got it wrong. Aggregators such as CoinGlass compile the liquidations that exchanges publish, and each outlet cuts its 24-hour window at a different time. That is why we only give Friday’s figure here, with its source and its window.
 What is a crypto liquidation? Leverage and margin
Leverage. It means trading with more money than you put in. With 10x leverage, €1,000 lets you open a €10,000 position. If the price rises 5%, you make €500; if it falls 5%, you lose €500, half of what you put in.
Initial margin. It is the collateral you put up to open the position. With 10x, 10% of the position: the €1,000 in the example.
Maintenance margin. It is the minimum that has to remain in the position for it to stay open. Each platform sets it. If your losses take you below it, the platform closes the position for you. That is the liquidation.
You can open two types of position:
- Long: you make money if the price rises. You get liquidated if it falls too far.
- Short: you make money if the price falls. You get liquidated if it rises too far.
And there are two ways of allocating margin:
- Isolated margin: each position has its own margin. If you are liquidated, you lose the margin of that position and nothing more.
- Cross margin: all your positions share the account balance. Liquidation comes later, because the platform draws on the rest of your balance, but when it comes it can take much more than the margin of a single trade.
If any term sounds like gibberish, you will find it explained in the crypto glossary with its tax reading.
 How the liquidation price is calculated: an example with €1,000
Let’s use round numbers, without fees and approximately. A crypto is worth €50,000. You open a long position with €1,000 of margin and 10x leverage. Your position is €10,000, that is, 0.2 units.
- If the price falls 10%, to €45,000, your position loses €1,000. That is all your margin.
- But the platform does not wait for you to hit zero: it closes you out when you touch the maintenance margin. If, for example, that minimum were 0.5% of the position, liquidation would come with a drop of around 9.5%, at about €45,250.
In a short position the same happens the other way round: you are liquidated with a similar rise.
The quick rule is to divide 100 by the leverage. That is, roughly, the drop that wipes out your margin: 50% with 2x, 20% with 5x, 10% with 10x, 5% with 20x and 2% with 50x. The real liquidation price is always a little closer, because you have to take off the maintenance margin, the fees and, in perpetuals, the funding.
 Perpetuals, dated futures and the funding rate
These are the three crypto derivatives you will see most often:
- Dated futures. Contracts to buy or sell at a set price on a future date. When that date arrives, the contract is settled and ends.
- Perpetual futures. The flagship product of crypto derivatives exchanges. They work like a future but never expire: the position stays open until you close it or you are liquidated.
- CFDs (contracts for difference). Offered by brokers. You agree with the broker that it will pay you, or you will pay it, the price difference between opening and closing. You do not buy the crypto either.
To stop a perpetual drifting away from the crypto’s price on the spot market there is the funding rate: a periodic payment between traders, every few hours depending on the platform:
- If the perpetual trades above spot, funding is positive: longs pay shorts.
- If it trades below, it is negative: shorts pay longs.
Watch out: funding is calculated on the size of the position, not on your margin. With 10x, you pay or receive on €10,000, not on €1,000. And what you pay comes out of your margin, so it also brings you closer to the liquidation price.
 Cascading liquidations: why the price falls like dominoes
When the platform liquidates a long position, it closes it by selling at market. Nobody decides that sale: it is automatic, and it pushes the price down.
The problem is that many traders have their liquidation prices close to one another. So the first batch of forced sales takes the price to the next batch of liquidations. Those sales push it a little further, and the next one is triggered. This is what is called chain or cascading liquidations.
It works the same way in reverse: if the price jumps, shorts are liquidated, they are closed by buying, and the price rises further. This is the famous short squeeze.
In November, it was a textbook cascade: almost everything liquidated was long positions.
 What do the rules say? MiFID II, MiCA and the CNMV
There is a very widespread confusion here. The European MiCA regulation, the one that requires exchanges to hold a licence, does not apply to derivatives. Its Article 2(4) excludes crypto-assets that are financial instruments, and futures, perpetuals and CFDs on cryptocurrencies are derivative financial instruments. They are governed by MiFID II, the directive on markets in financial instruments, like a future on a share.
That is why an exchange holding a MiCA licence says nothing about its derivatives. We explain it in which exchanges have a MiCA licence in Spain.
For retail clients, Europe has been setting limits for years:
- ESMA restricted the sale of CFDs to retail clients across the EU in 2018 with temporary measures. National supervisors then adopted those same measures as their own.
- In Spain, the CNMV (Spanish securities regulator) did so with its Resolution of 27 June 2019 (BOE-A-2019-9737). For a CFD on a cryptocurrency, the minimum initial margin is 50% of the position. That is equivalent to maximum leverage of 2:1. It also requires the broker to close the position when the margin falls to half of the initial amount, and it limits what a retail client can lose to what they have deposited in their CFD account.
- On 24 February 2026, ESMA warned that derivatives sold as “perpetuals” are likely to fall within those CFD measures. What counts is how the product works, not its name (ESMA statement).
Compare that 2:1 with the up to 40x allowed by a decentralised platform like the one we described in what is Hyperliquid. That difference is the protection you lose outside the European framework.
 How are futures and perpetuals taxed in the Spanish income tax return?
First, in all honesty: as of 16 November 2026 we have not found any published DGT ruling on futures, perpetuals or CFDs with cryptocurrencies as the underlying asset. The closest is binding ruling V0597-18, of 6 March 2018, on CFDs on indices and shares and on currency contracts. Applied by analogy, it gives these guidelines:
- Type of income. If the margin only serves as collateral, the result of each contract is a capital gain or loss (Article 33.1 of the IRPF Law). It is not income from movable capital.
- Savings tax base. The DGT includes those gains and losses in the savings tax base, under Article 46(b) of the law, just like the sale of cryptocurrencies.
- Calculation. The result is the difference between the value at which you open and the value at which you close the contract. Opening and closing fees count towards the calculation.
- When it is declared. In the year in which the right to collect or the obligation to pay arises. If the platform settles results every day, the DGT considers that there is a gain or loss every day.
And a forced liquidation? It is a closure of the position, only the platform decides it. We have not found any rule or ruling that treats it differently from a voluntary closure. Applying the CFD criterion by analogy, the negative result of the contract would be a capital loss in the year of the liquidation. If it goes to the savings tax base, it is offset against your other capital gains for the year, including those from selling crypto, and whatever is left over follows the rules of Article 49: up to 25% of income from movable capital and four years of carry-forward. You have it in how to offset crypto losses in your tax return. To benefit from it, you have to declare it.
And funding? There is no published criterion here, and V0597-18 itself leaves two possible readings. In CFDs, the interest you pay to keep the position open overnight does not count, because the DGT sees it as a financing cost. In currency contracts, by contrast, the daily payment for the interest rate differential does form part of the gain or loss. A perpetual’s funding does not fit neatly into either case, and nobody has said which one applies. If you have paid or received it, keep the details and get advice.
Two more points:
- Margin in crypto. If you swap a crypto for a stablecoin to use it as margin, that is a swap (permuta) and is taxed in its own right (DGT V0999-18). And if the margin is a crypto, such as BTC, and the liquidation takes it, there is no published criterion on how it is calculated. It is a case to review one by one.
- Foreign brokers. If you trade CFDs with a foreign investment firm, the DGT considers that the cash account the broker keeps for you is an account abroad that may have to go on Modelo 720 (the Spanish return on assets held abroad), with its thresholds and exclusions (ruling V1950-24).
Summary: the essentials of a crypto liquidation
| Concept | What it means | What to bear in mind |
|---|---|---|
| Leverage | Trading with more money than you put in | Multiplies gains and losses |
| Initial margin | Your collateral to open the position | With 10x, 10% of the position |
| Maintenance margin | The minimum to stay open | Below it, the platform liquidates you |
| Liquidation price | The price at which you are closed out | With 10x, a little under 10% against you |
| Funding rate | Periodic payment between longs and shorts | Calculated on the position, not on the margin |
| EU regulation | MiFID II, not MiCA | Retail crypto CFDs in Spain: 2:1 maximum |
| IRPF (by analogy with CFDs) | Capital gain or loss, savings tax base | DGT V0597-18; no specific ruling for crypto |
| Forced liquidation | Closure decided by the platform | By analogy with CFDs, it would be declared and a loss could be offset |
 Frequently asked questions
If I get liquidated, can I lose more than I put in?
With isolated margin, you normally lose the margin of that position. With cross margin, the platform can use the whole balance of your account. With CFDs sold to retail clients in Spain, the CNMV’s measures limit your loss to what you have deposited in the CFD account.
One of my positions was liquidated, do I have to declare it?
By analogy, yes. There is no specific ruling on crypto derivatives, but under the criterion the DGT applies to CFDs the result of each contract is a capital gain or loss, and a forced liquidation is also a closure. Declaring it would let you offset that loss against your gains.
Are crypto futures taxed in the general tax base?
For CFDs on indices and shares, the DGT says they go to the savings tax base (V0597-18). There is no specific ruling for derivatives on cryptocurrencies, but it is the closest criterion there is.
I have a position open on 31 December, is it taxed this year?
In general, the gain or loss is declared in the year in which the contract is closed or settled. If your platform settles results periodically, each settlement could count on its own date, as the DGT says for CFDs with daily settlement.
Get your derivatives in order before your tax return
Derivatives are the hardest thing to declare: hundreds of positions, funding every few hours and liquidations nobody summarises for you. Send us your history and we will generate the document with all your exchanges and wallets using the global FIFO method required by the Spanish tax authority.
Sources: CoinDesk: Bitcoin falls below $70,000 as dollar surges and $1.6 billion liquidated (13/11/2026) · DGT, binding ruling V0597-18 · ESMA: reminder on the CFD product intervention measures (24/02/2026)

Víctor Lázaro
Marketing Director, Cryptoimpuestos.es



